Nikki Farag Agency
Call Anytime 310-390-4500
Nikki Farag Agency
Call Anytime 310-390-4500
Flooding isn’t just a risk in coastal or hurricane-prone regions — it’s a growing concern across Southern California, including the Los Angeles area. Intense rainstorms, urban runoff, aging stormwater systems, and wildfires (which destabilize hillsides) all increase flood risk, even in areas not officially mapped as high-risk zones. Yet most homeowners insurance policies do not cover flood damage.
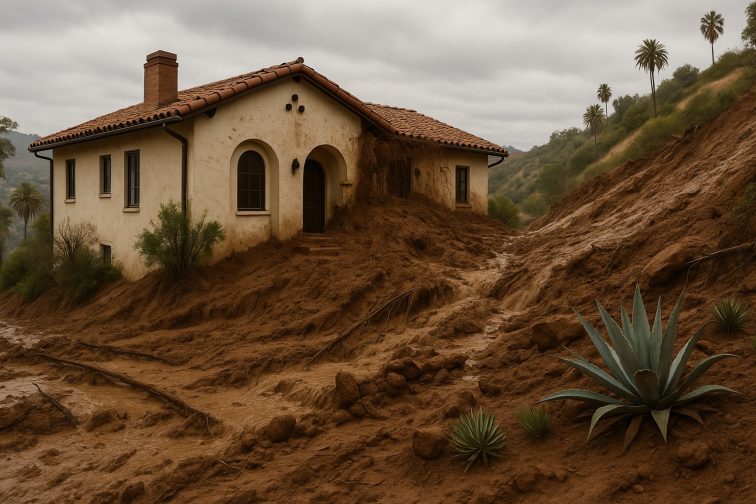
You don’t have to live in a high-risk flood zone to benefit from coverage. In fact, over 20% of flood claims come from properties outside of mapped flood zones. You should consider flood insurance if:
You live near canyons, creeks, or burn areas from past wildfires
Your neighborhood has poor drainage or has experienced recent flooding
You live in a low-lying or densely paved area of L.A., such as parts of Studio City, Culver City, or Baldwin Hills
You rely on sump pumps or storm drains to manage heavy rainfall
We help homeowners, renters, landlords, and condo owners get the protection they need.
Flood insurance helps protect your property and belongings from water damage caused by:
Flash floods
Heavy rain and runoff
Storm drain backups (when directly caused by flooding)
Overflow from nearby bodies of water
Mudflows related to flooding
Flood insurance coverage in Los Angeles helps with:’
Repairs to your home’s structure
Electrical and plumbing systems
HVAC systems, water heaters, and appliances
Personal property like furniture, electronics, and clothing
Foundation, crawl spaces, and detached garages
Flooding can happen when you least expect it—especially in areas affected by heavy rain, mudslides, or rising groundwater. Unfortunately, most homeowners policies don’t cover flood damage, which is why having a separate flood insurance policy is so important. I’m here to help you understand the risks in your area and find coverage that gives you peace of mind. If you live in a flood-prone zone or just want to be prepared, let’s make sure you have the protection you need.
Nikki Farag
Farmers Insurance Agency Owner
License 4247364
At Nikki Farag Insurance Agency, our clients are at the heart of everything we do. From personalized guidance to reliable coverage, we’re proud to earn the trust of families and business owners across Greater Los Angeles. Here’s what some of our customers have shared about their experience working with us.
Reviews
Nikki and her team are absolutely fantastic. I’ve been with them for both my auto and home insurance for years, and they’ve always been incredibly responsive and helpful. Whether I need an extra copy of an insurance card, or just have a quick question, they’re always patient and easy to reach. I can’t recommend Nikki enough!
Reviews
I was referred to Nikki by a coworker who’s one of her clients, and I’m so glad I made the switch. I moved all of my policies over from State Farm because I really value the personalized service Nikki and her team provide. It’s refreshing to work with someone who takes the time to explain everything and is genuinely invested in helping you. I also love that she’s local—there’s a real sense of connection and trust.

Reviews
Nikki has been our insurance agent for just about a year now and we love the personal service we get with her. We have our home, autos and our landlord policies all with her through Farmers and I would highly recommend her to anyone who is looking for insurance!
Reviews
Amazing service! Got my five work trucks covered and got me a policy for my home insurance. Thank you Nikki you are a pleasure to work with 10/10 would recommend to anyone!!!
Mudslides are generally excluded under standard flood policies but mudflows (a flood-related event) may be covered. We’ll help you understand the distinction and explore options for broader protection.
If your home is located in a high-risk flood zone (Special Flood Hazard Area) and your mortgage is backed by a federal lender (like Fannie Mae or Freddie Mac), flood insurance is usually required by law. Your lender will require you to maintain coverage for the life of the loan.
Even if you’re not in a high-risk zone, your lender may still encourage you to get coverage. And if you own your home outright, flood insurance is entirely optional — but still highly recommended if you live near hillsides, rivers, drainage basins, or recently burned areas.
If you rent in a flood-prone area, you can and should purchase a renters flood insurance policy. This type of policy covers:
Your personal belongings (furniture, electronics, clothes, etc.)
Storage contents (depending on policy terms)
It does not cover the building itself — that’s your landlord’s responsibility. Many renters mistakenly assume they’re protected by their landlord’s insurance, but in a flood, your personal items are not covered unless you have your own renters flood insurance policy.
No — flood insurance only covers damage from rising water that affects two or more properties (or two or more acres), as defined by FEMA.
If water enters your home because of a leaking roof, broken window, or poor maintenance, the damage would be considered water damage, not flood damage, and typically would be handled by your homeowners insurance — if it’s covered at all. It’s important to understand how these policies work together, and we’ll help you sort that out.